
Washington Homeowners Insurance Endorsements You Might Need
Your standard homeowners insurance policy covers the basics, but it often leaves gaps for Washington homeowners. That’s where endorsements come in-they’re add-ons that extend your protection to match your specific situation.
At Aurora National Insurance, we’ve seen too many homeowners discover they’re underinsured after a loss. The right Washington homeowners insurance endorsements can mean the difference between being protected and facing unexpected out-of-pocket costs.
What Endorsements Actually Do
Endorsements are specific additions to your base homeowners policy that cover situations your standard coverage ignores. They’re not optional upgrades for the ultra-wealthy-they’re practical protections that address real gaps in typical policies.
A standard homeowners policy covers your home’s structure, personal belongings, liability, and additional living expenses if you need to relocate temporarily. But it comes with strict limits and exclusions. Your jewelry coverage maxes out around $1,500 total, water damage from flooding isn’t covered at all, and home-based businesses receive zero liability protection. Endorsements fix these problems by extending coverage limits or adding entirely new protections.
If you run a consulting business from your home office, a standard policy leaves you exposed to lawsuits-an endorsement adds the coverage you actually need. The same applies to valuable collections, high-end electronics, or homes in flood-prone areas of Washington.
Why Standard Policies Leave You Exposed
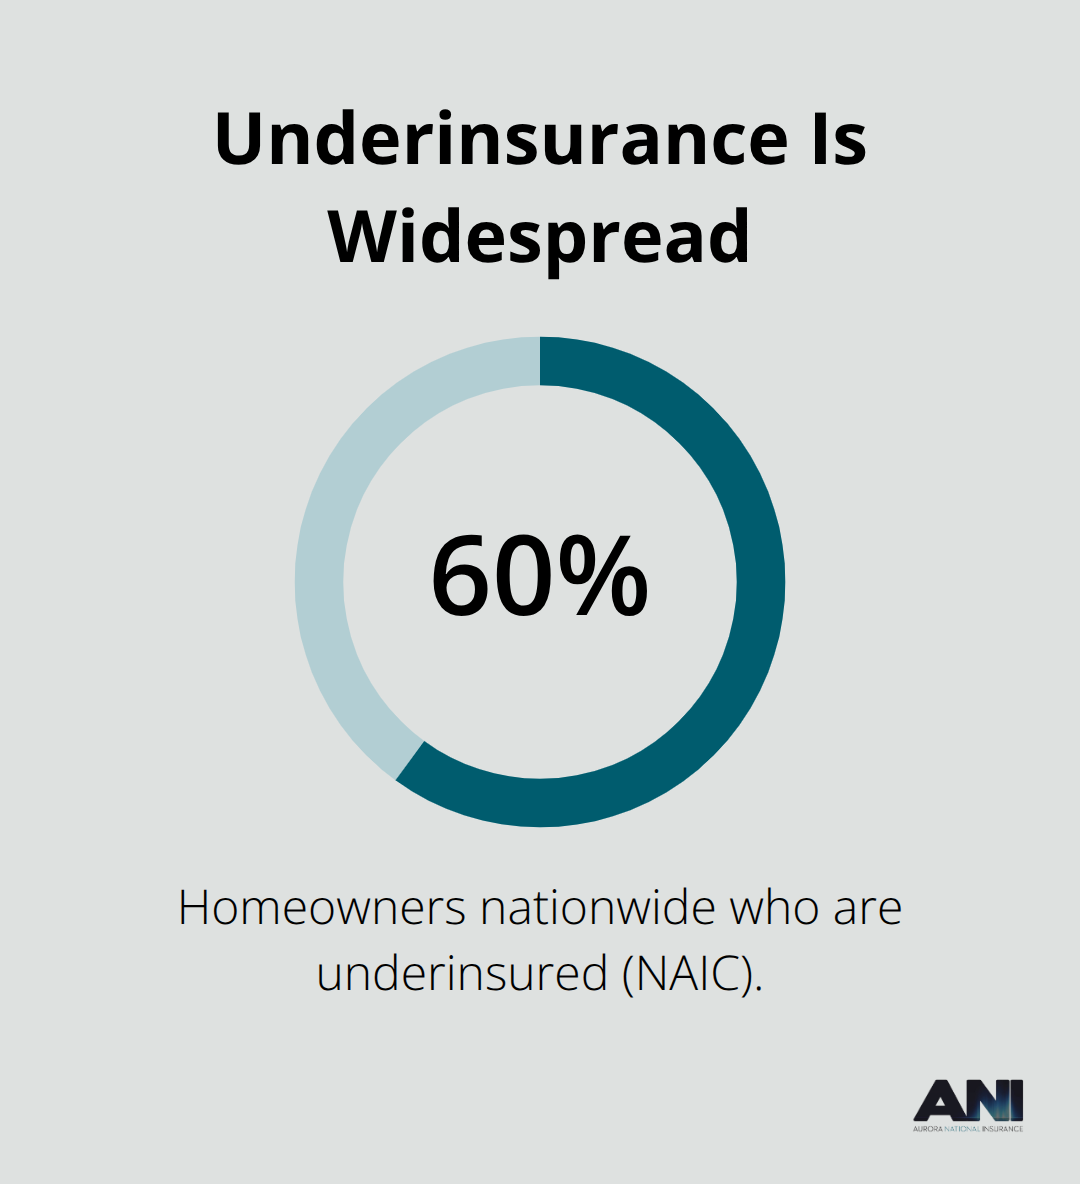
Most homeowners buy whatever policy their agent recommends without questioning what’s missing. The National Association of Insurance Commissioners reports that underinsurance affects roughly 60% of homeowners nationwide, and Washington homeowners face specific regional risks that standard policies don’t address.
Windstorms are common in coastal Washington counties, yet standard policies cap wind damage coverage. Homes near rivers or in low-lying areas face flooding, which standard policies explicitly exclude. Older homes with outdated electrical systems or plumbing need specialized coverage that basic policies won’t touch.
Standard policies also place strict sublimits on high-value items-that $3,000 camera equipment collection or $5,000 in tools stored in your garage receives minimal protection. The coverage exists, but the limits are unrealistically low. Endorsements let you increase these limits or add coverage categories entirely.
The Gap Between What You Own and What You’re Protected For
Your possessions likely exceed what your standard policy covers. Most homeowners own items worth far more than their policy’s sublimits allow. A single piece of jewelry, a collection of tools, or electronics can quickly surpass the $1,500 jewelry limit or the general personal property cap. Endorsements close this gap by letting you specify high-value items and set appropriate coverage limits for them. This targeted approach means you pay only for the protection you actually need, rather than overpaying for broad coverage that doesn’t fit your situation. Understanding which endorsements match your specific assets is the first step toward real protection.
Three Endorsements Washington Homeowners Actually Need
Water Damage and Flood Protection
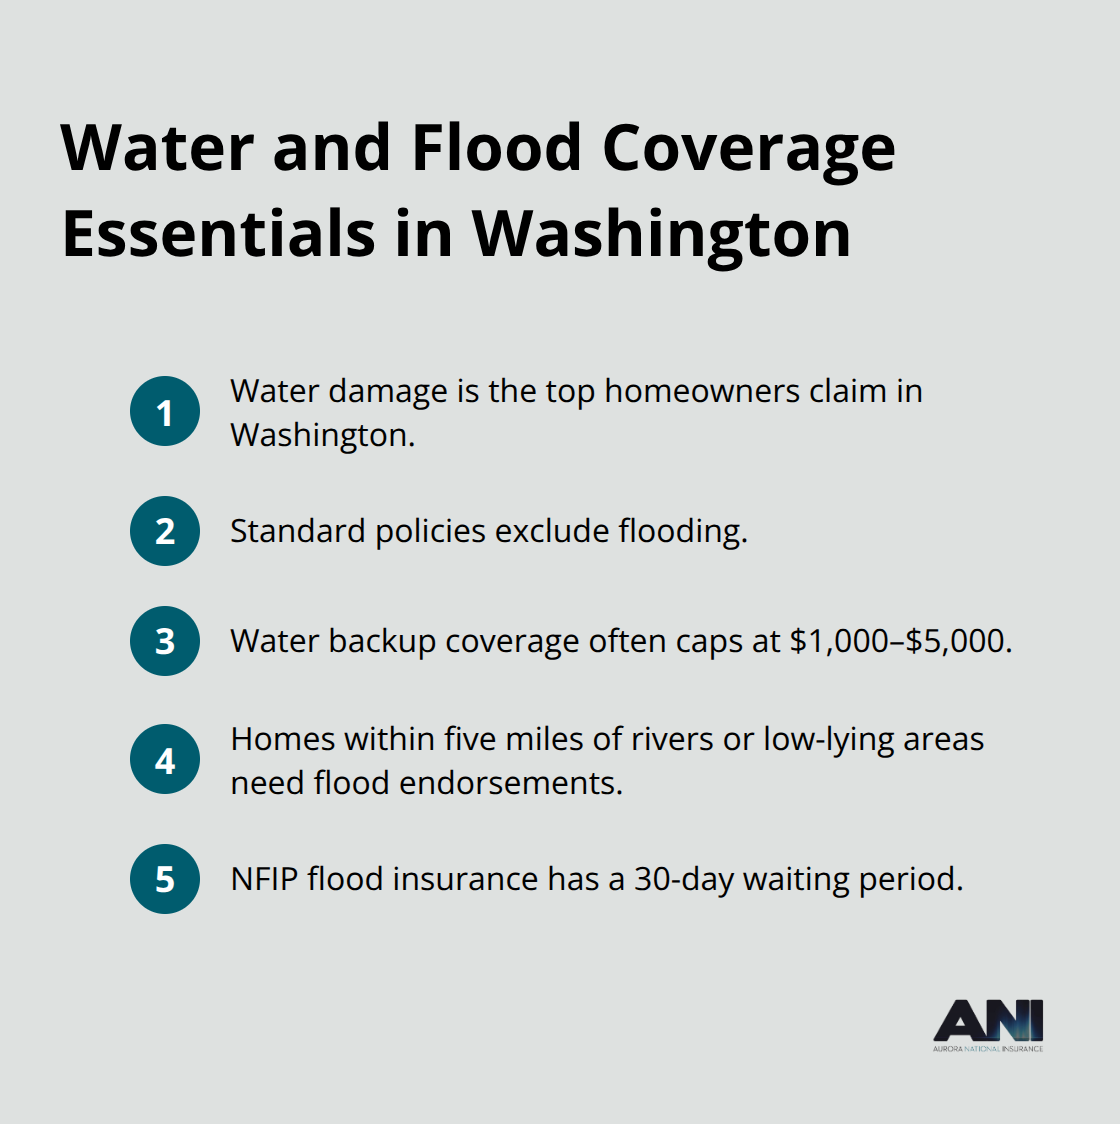
Water damage ranks as the top homeowners insurance claim in Washington, yet standard policies exclude the most common culprit-flooding. Most homeowners policies cap water backup coverage at $1,000 to $5,000. If you live within five miles of a river, creek, or in a low-lying area of King, Pierce, or Snohomish counties, a flood endorsement isn’t optional.
Pairing flood coverage with a water backup endorsement protects you against damage from sump pump failures, backed-up sewers, and overflowing drains-situations that hit Pacific Northwest homes regularly. Flood insurance through the National Flood Insurance Program requires a 30-day waiting period, so waiting until after heavy rains arrive leaves you unprotected when you need it most.
Scheduled Personal Property for High-Value Items
High-value items get crushed under standard policy limits. Your engagement ring appraised at $8,000 falls under the $1,500 jewelry sublimit, leaving you $6,500 short if theft or damage occurs. A scheduled personal property endorsement lists specific items with individual coverage limits, and insurers won’t apply sublimits to scheduled goods.
If you own jewelry, watches, cameras, art, or collections worth more than $2,000 per category, this endorsement pays for itself through better protection. You’ll need appraisals for items over $500, but that documentation also protects you during claims.
Home Business Liability Coverage
Home-based business owners face steep gaps in standard coverage-a typical policy provides zero liability protection if a client gets injured at your home office or suffers losses from your work. A home business endorsement adds liability protection and covers equipment and supplies used for your business.
If you run any business activity from home (consulting, freelancing, tutoring, or anything else generating income), your standard homeowners policy actively excludes those activities from coverage. This gap exposes you to significant financial risk that a business endorsement eliminates. Determining which endorsements match your specific situation requires honest assessment of your home, possessions, and activities.
Which Endorsements Match Your Situation
Inventory Your High-Value Possessions
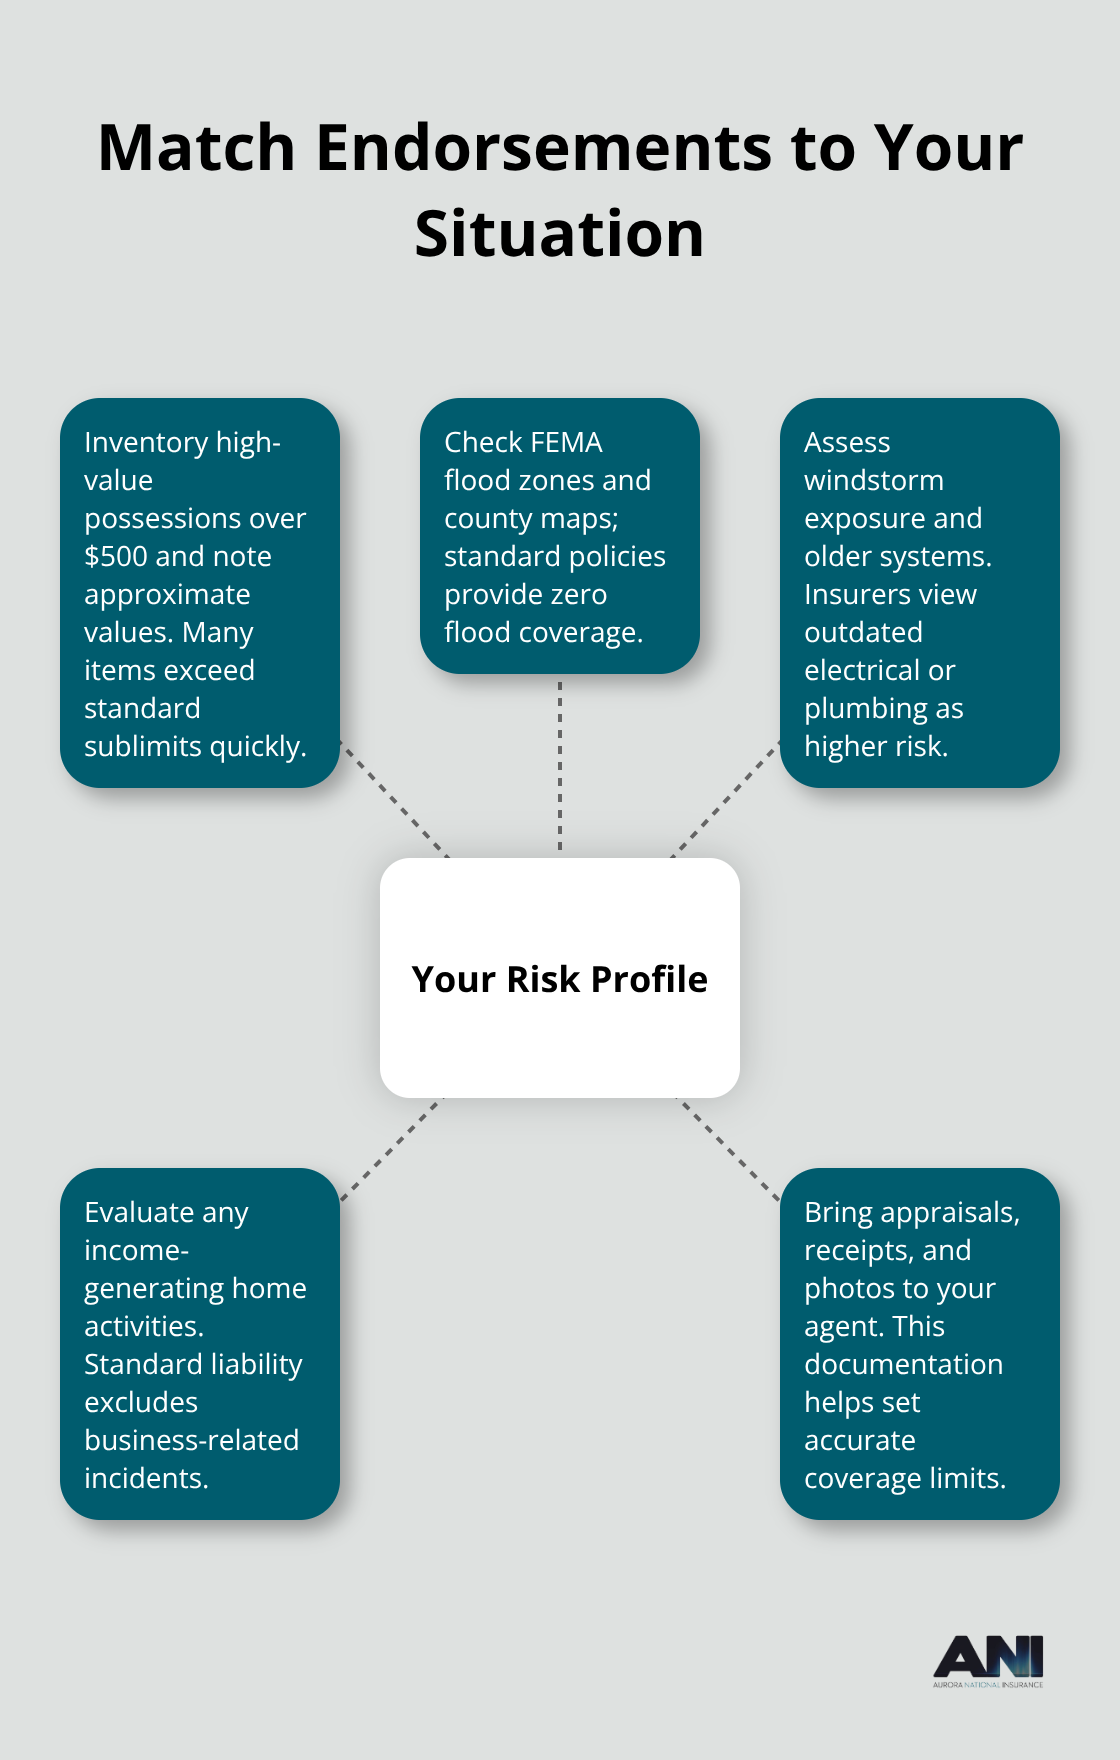
List everything you own that costs more than $500. This single action reveals what standard policies won’t adequately protect. Your engagement ring, camera equipment, tools, collectibles, and electronics should all appear on this list with their approximate values. Most homeowners discover their high-value items exceed standard sublimits within minutes of completing this exercise.
Assess Your Home’s Regional Vulnerabilities
Washington homeowners face distinct regional risks that standard policies either exclude or severely limit. If your property sits within a flood zone designated by FEMA, flood coverage isn’t negotiable-you need it before the next heavy rain arrives. Check your county’s flood maps online; King County, Pierce County, and Snohomish County have extensive flood-prone areas where standard policies provide zero protection.
Coastal properties face windstorm damage that standard policies cap at low limits, sometimes as little as 10% of your home’s replacement value. Older homes with original electrical systems or plumbing from decades ago need specialized coverage because insurers view them as higher-risk for fire or water damage. Document your home’s age, construction materials, and any recent upgrades when assessing risk-this information directly determines which endorsements make financial sense.
Evaluate Your Home-Based Work Activities
If you earn any income from home-based work, your standard policy excludes liability protection for that activity. Tutors, consultants, freelancers, and small business owners operating from home all fall into this category. The cost of a home business endorsement typically ranges from $200 to $400 annually, yet a single lawsuit from a client could cost tens of thousands of dollars without it. Treating this endorsement as non-negotiable makes financial sense if you generate income at home.
Connect with Your Insurance Agent
Schedule a conversation with your agent specifically about flood zones, high-value possessions, and business activities-don’t assume your current policy covers these situations. Bring documentation like appraisals, receipts, and photos of valuable items to this conversation. Your agent can then recommend specific endorsements with accurate coverage limits based on your actual risk profile and assets.
Final Thoughts
Washington homeowners insurance endorsements address real gaps that leave most homeowners underprotected. Start by reviewing your current policy this week and pull out your declarations page to compare what’s actually covered against what you own and where you live. Check whether your high-value items fall within standard sublimits, confirm your flood zone status, and honestly assess any income-generating activities happening at home.
Contact your insurance agent with specific questions rather than general inquiries, and bring documentation of valuable items along with your home’s age and construction details. Your agent can then recommend endorsements that match your actual risk profile instead of suggesting generic add-ons that don’t fit your situation. The cost of adding the right endorsements typically ranges from a few hundred dollars annually-far less than the financial damage from being underinsured when something goes wrong.
Contact Aurora National Insurance to review your Washington homeowners insurance endorsements today. Our licensed agents compare coverage options from multiple carriers and help you understand exactly what each endorsement costs and covers. Your home and possessions deserve protection that actually matches what you own and where you live.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.


