
Washington Home Insurance Guide: A Local Perspective
Washington homeowners face unique insurance challenges, from windstorms to earthquakes to potential flooding. Getting the right coverage protects your home and finances against these regional risks.
At Aurora National Insurance, we’ve created this Washington home insurance guide to help you understand what coverage you actually need and how to find affordable rates. Whether you’re a first-time buyer or reviewing your current policy, this guide walks you through the essentials.
What Coverage Do Washington Homeowners Actually Need
Mandatory Dwelling Coverage for Mortgaged Homes
Washington lenders require homeowners with mortgages to carry dwelling coverage that protects the structure itself-the walls, roof, foundation, and built-in systems. Your lender will force you to buy it before closing. The minimum amount typically matches your loan balance, though we recommend covering the full replacement cost of rebuilding your home from scratch, not just what you owe on the mortgage.
Choosing Between HO-3 and HO-5 Policies
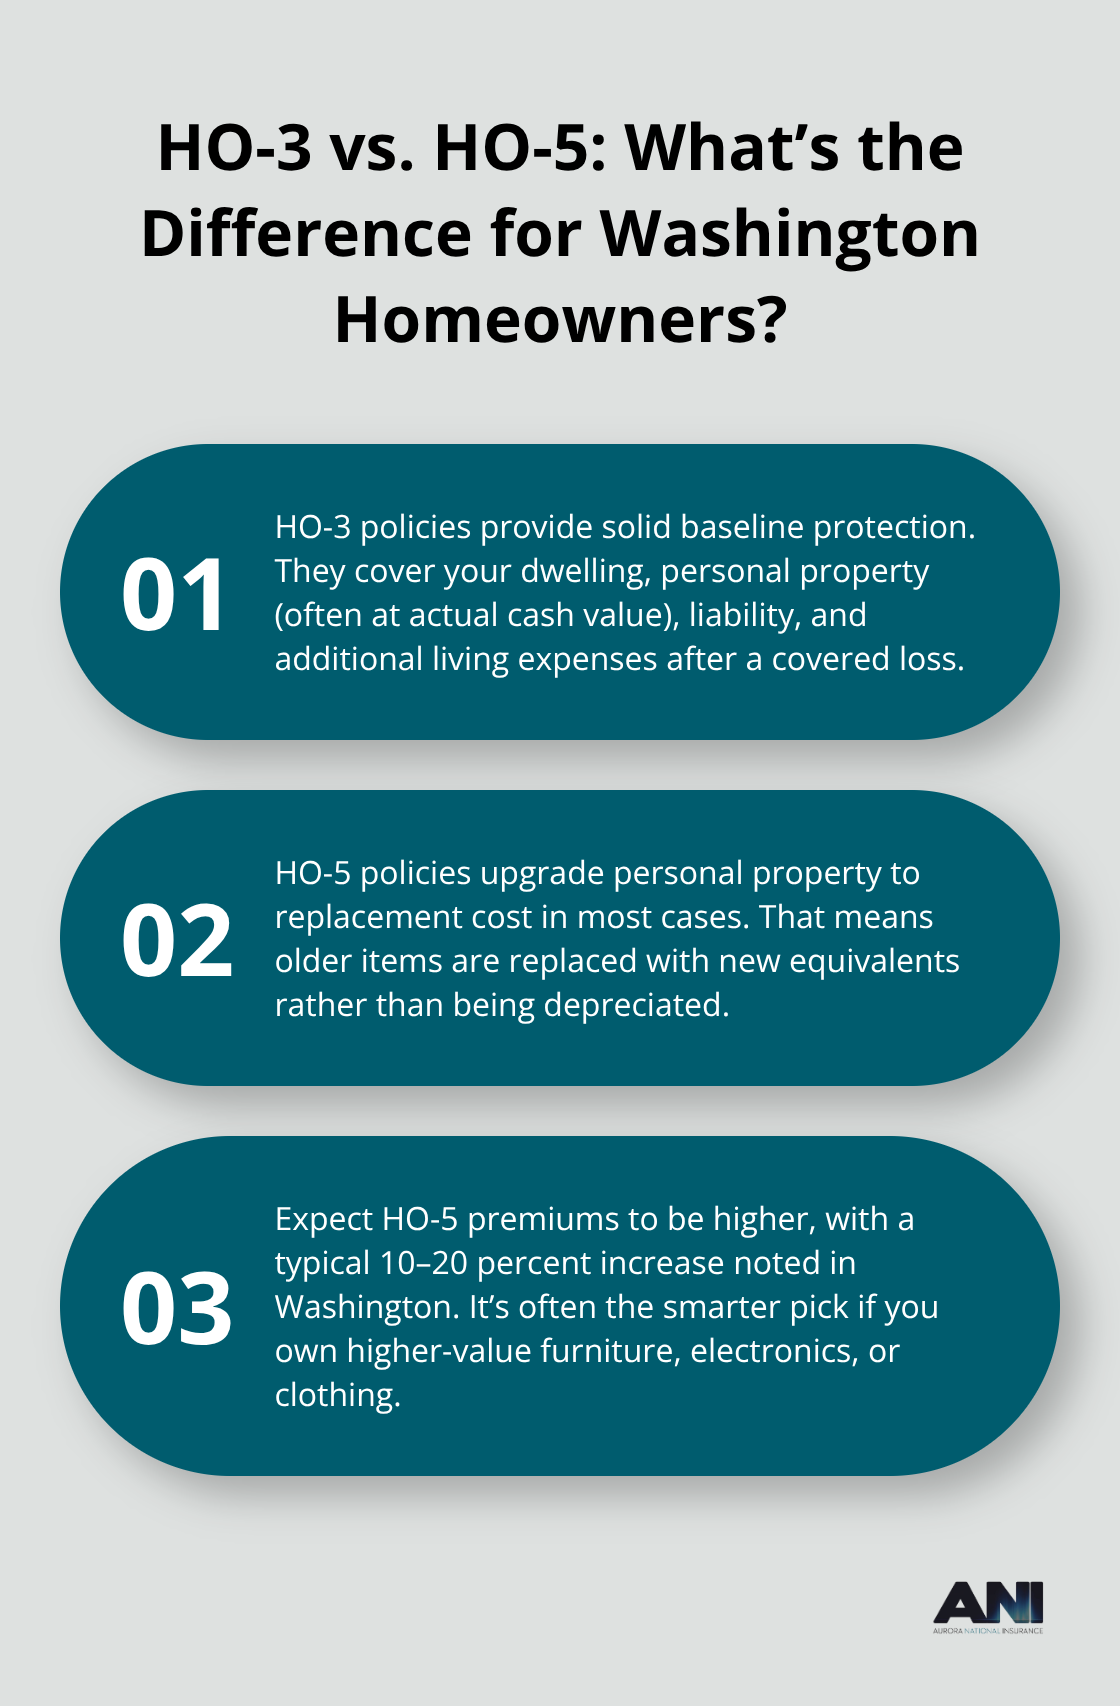
Most Washington homeowners choose HO-3 policies, which cover the dwelling, personal property inside the home, liability protection if someone gets hurt on your property, and additional living expenses if you need temporary housing after a covered loss. HO-5 policies go further by offering replacement cost coverage for personal belongings instead of actual cash value, meaning your ten-year-old couch gets replaced with a new one rather than depreciated to a fraction of its original price. The difference in premium between HO-3 and HO-5 typically ranges from 10 to 20 percent annually, making HO-5 the stronger choice if you own valuable furniture, electronics, or clothing.
Additional Coverage Options Worth Considering
Washington homeowners often add water backup coverage, which protects against sewer backups and sump pump failures-a real problem in areas with heavy rainfall. You should also consider adding an umbrella policy of one to two million dollars if you have significant assets, since standard homeowners liability maxes out at 300,000 dollars. This costs roughly 150 to 300 dollars annually and protects your savings and future income if someone sues you for damages.
Beyond these standard additions, Washington’s specific weather patterns create additional coverage needs that vary significantly by region.
Washington Weather Threats and Your Insurance Response
Windstorm and Hail Coverage in Western Washington
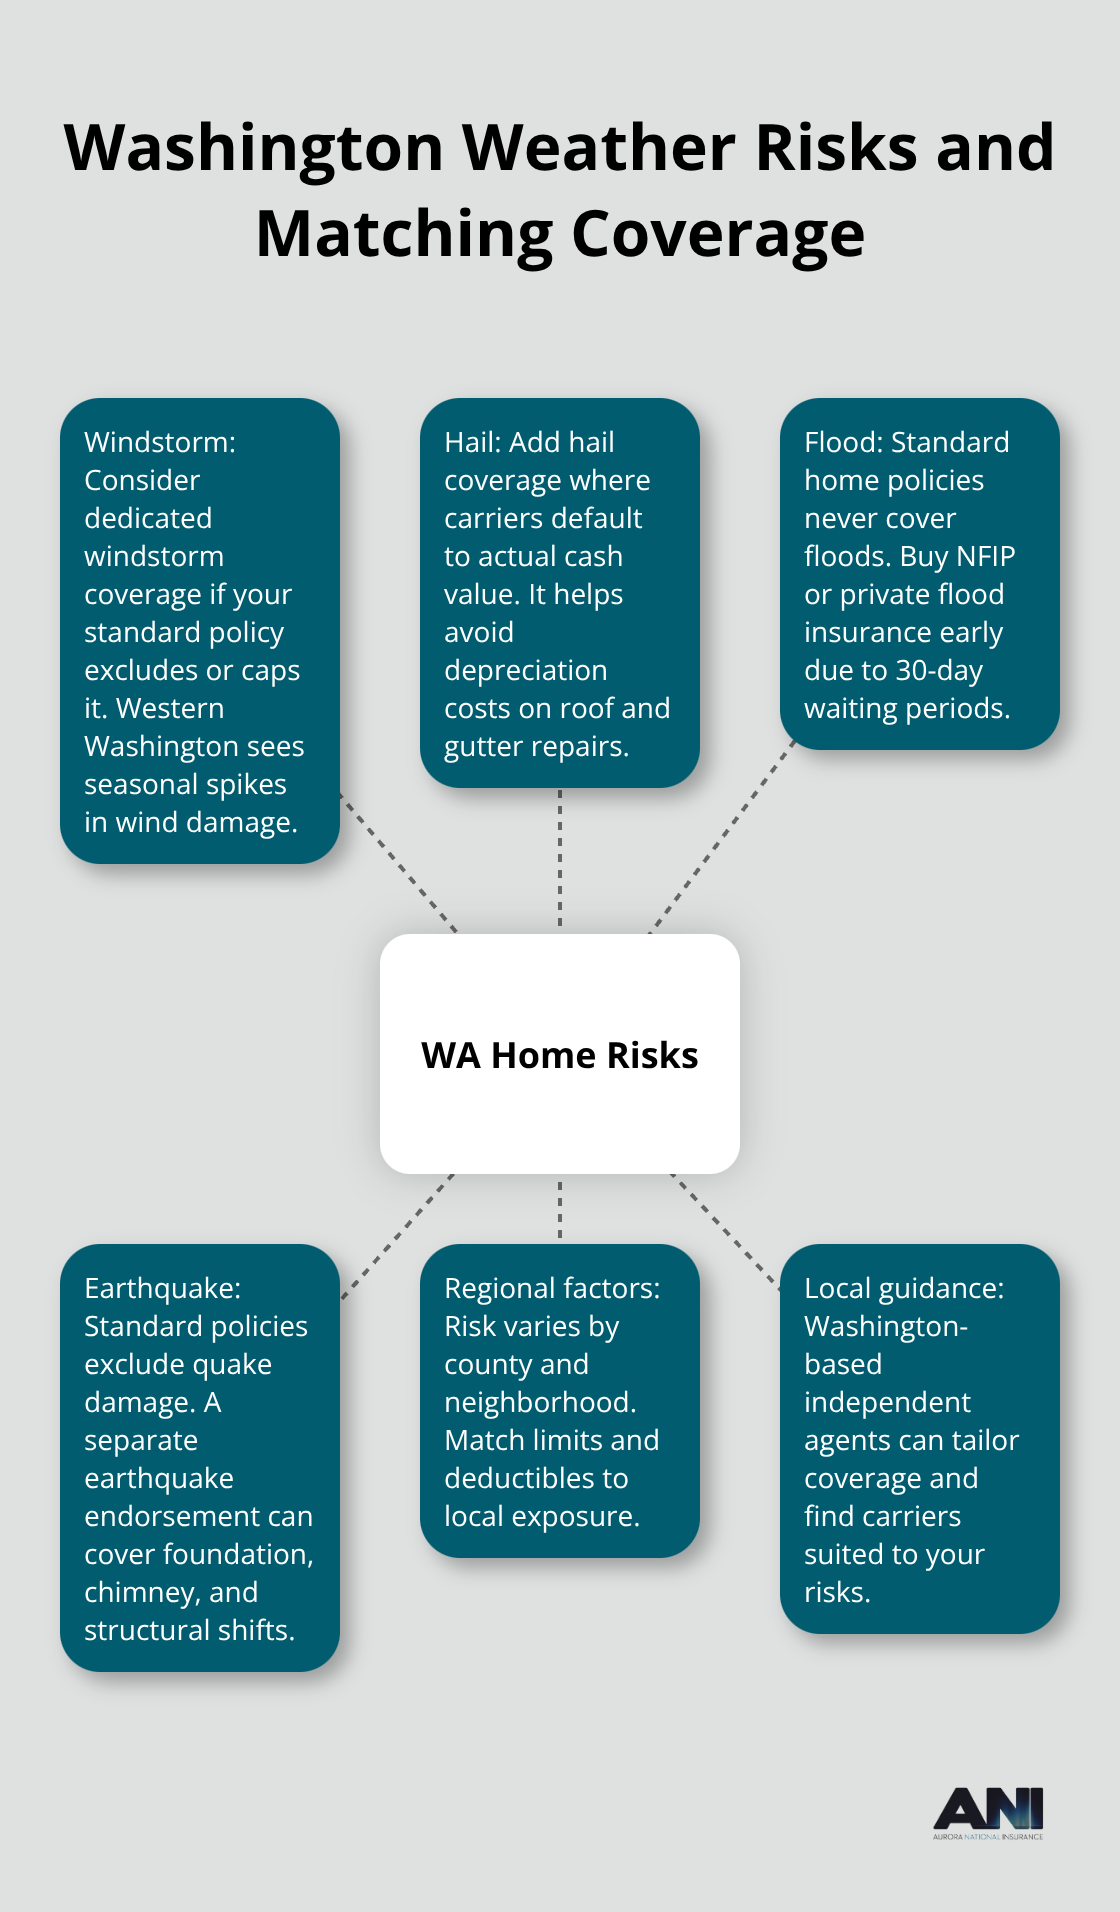
Washington’s Pacific coast location exposes homeowners to windstorms that standard policies often exclude or limit. Windstorms regularly damage roofs and siding across western Washington, with the December 2006 windstorm causing significant insured losses in Washington and Oregon. Most standard HO-3 policies cap windstorm coverage or exclude it entirely, leaving you responsible for thousands in repairs. If your home sits in western Washington-particularly in King, Pierce, or Snohomish counties-add specific windstorm and hail coverage, as wind damage claims spike between October and March. This coverage typically adds 150 to 400 dollars annually depending on your roof’s age and material, but protects against the exact damage your basic policy won’t touch.
Hail also damages roofs and gutters across central and eastern Washington during spring months. Many carriers limit hail claims to actual cash value rather than replacement cost, meaning you absorb depreciation on repairs. Adding hail coverage protects you from these seasonal risks that your standard policy may not address adequately.
Flood Insurance in High-Risk Areas
Flood insurance requires immediate attention if you live in a Federal Emergency Management Agency designated high-risk zone, which includes areas near the Snoqualmie River, Duwamish River, and coastal regions. Standard homeowners policies never cover flooding, and your mortgage lender will require flood insurance if you’re in a high-risk area. The National Flood Insurance Program charges roughly 400 to 2,000 dollars annually for residential coverage depending on elevation and flood history. You must wait thirty days after purchase before coverage activates, so delaying this decision costs you protection during that critical window.
Earthquake Coverage for Cascadia Subduction Zone Risks
Earthquake coverage stands apart because Washington sits directly on the Cascadia Subduction Zone and experiences frequent smaller quakes that damage foundations and chimneys. Standard policies exclude earthquake damage, and adding this coverage costs between 100 and 300 dollars yearly but covers foundation repairs, chimney damage, and structural shifts that otherwise fall entirely on you. Local agents understand which neighborhoods face the highest earthquake risk and can recommend appropriate coverage limits for your specific location.
These regional weather threats create distinct insurance needs that vary significantly by neighborhood. Finding affordable coverage that actually protects against these specific risks requires comparing quotes from multiple carriers and understanding what discounts apply to your situation.
Finding Affordable Home Insurance in Washington
Comparing Quotes from Multiple Carriers
Multiple quotes from different carriers reveal rate variations that most Washington homeowners never see. When you request quotes from three or more insurers, you typically spot rate differences of 30 to 50 percent for identical coverage. A homeowner in Seattle might pay $1,200 annually with one carrier and $800 with another for the same HO-3 policy with identical limits. The only way to find these differences is to compare actual quotes side by side, not estimates or sample rates from websites.
Contact carriers directly or work with an independent agent who represents multiple companies. Independent agents can pull quotes from five to ten insurers simultaneously rather than forcing you to call each one individually. This process takes roughly 30 minutes but saves an average of $482 on home insurance and continues saving money year after year.
Discounts Available to Washington Residents
Washington-specific discounts exist but require you to ask for them explicitly. Agents rarely volunteer information about discounts unless you prompt them. Bundling your home and auto policies with the same carrier typically saves 10 to 25 percent on your home premium.
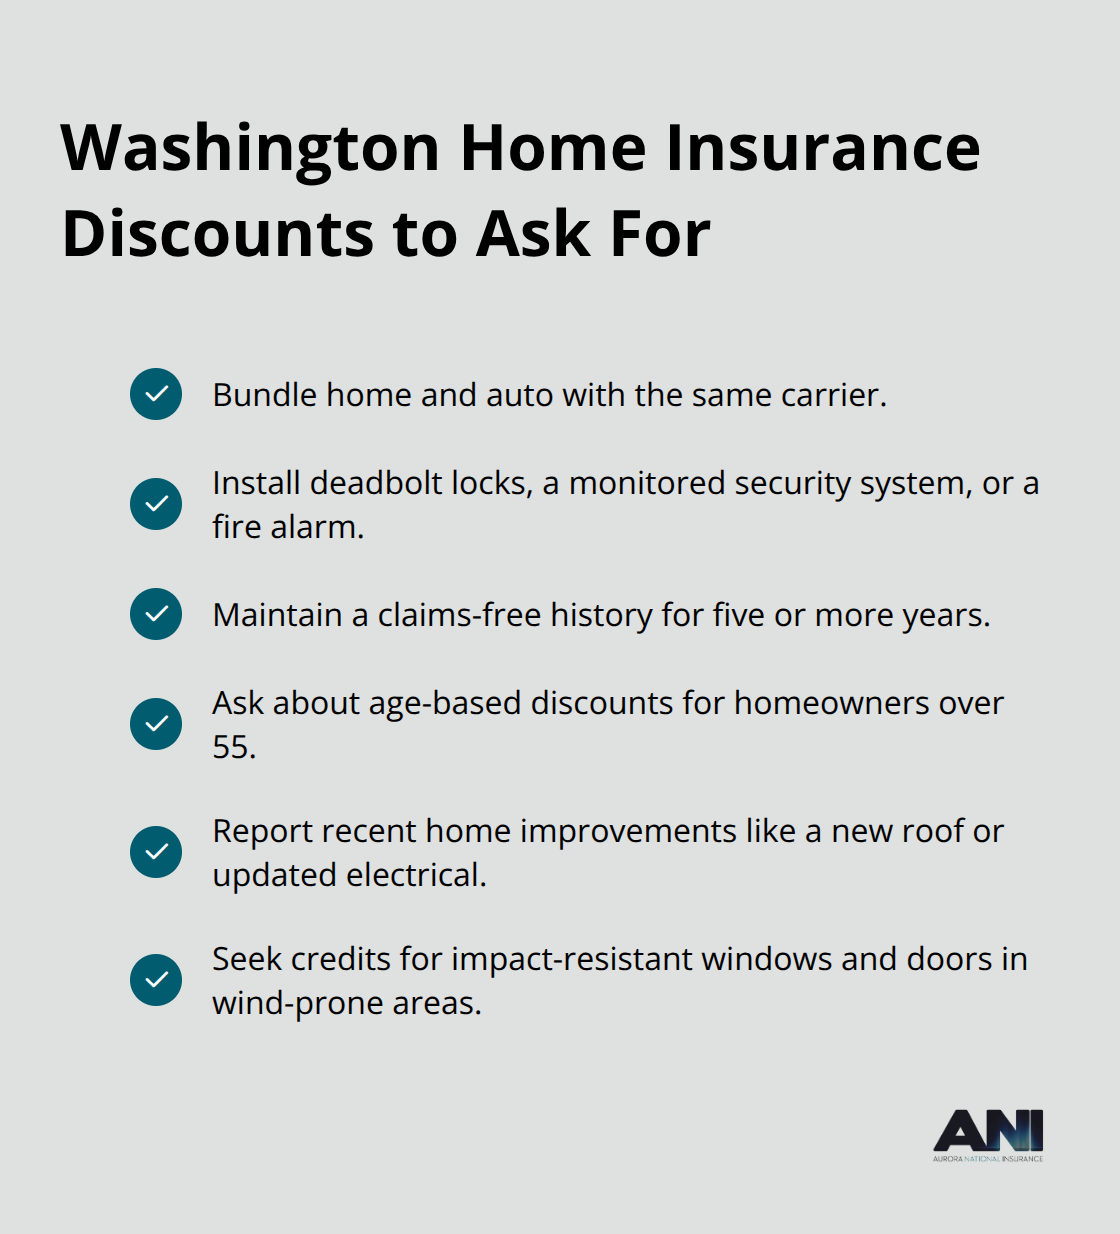
Installing deadbolt locks, a security system, or a fire alarm can reduce rates by 5 to 15 percent depending on the equipment and your carrier. Some insurers offer discounts for homeowners over 55, claims-free histories stretching five or more years, or recent home improvements like new roofs or updated electrical systems. A few carriers provide discounts specifically for homes with impact-resistant windows and doors (which matter significantly in windstorm-prone areas of western Washington).
Your current insurer won’t automatically apply these discounts either. Contact them directly and ask which ones you qualify for, then verify your renewal quote reflects each one.
Working with Local Agents for Personalized Coverage
Local agents understand Washington’s specific insurance landscape and can identify which discounts apply to your situation rather than leaving money on the table. An independent agent licensed in Washington can represent multiple top-rated carriers and pull comparisons that match your home’s unique risks (from earthquake exposure to windstorm vulnerability to flood zones). This approach saves time and typically uncovers coverage options and discounts you wouldn’t find on your own.
Final Thoughts
Washington homeowners face distinct insurance challenges that differ significantly from other regions. Your coverage needs depend on where you live-western Washington residents prioritize windstorm protection, those near rivers need flood insurance, and everyone in the state should consider earthquake coverage given the Cascadia Subduction Zone risk. Standard HO-3 policies provide a foundation, but HO-5 policies deliver better protection for personal belongings if you own valuable items.
Request quotes from at least three different carriers to identify the 30 to 50 percent rate variations that exist for identical coverage. Ask explicitly about discounts you qualify for-bundling, security systems, claims-free history, and home improvements all reduce premiums when you mention them. Work with a local agent who understands Washington’s specific risks and can match your home’s location and characteristics to appropriate coverage limits.
We at Aurora National Insurance help Washington homeowners navigate these decisions through personalized insurance comparisons. Our licensed agents represent multiple top-rated carriers and deliver tailored coverage that accounts for your neighborhood’s unique risks, whether that’s earthquake exposure in Seattle, windstorm vulnerability in Tacoma, or flood danger near river valleys. Start by comparing quotes today rather than waiting until renewal time forces the decision.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.


